How to find the cheapest mobile home insurance near you by comparing quotes
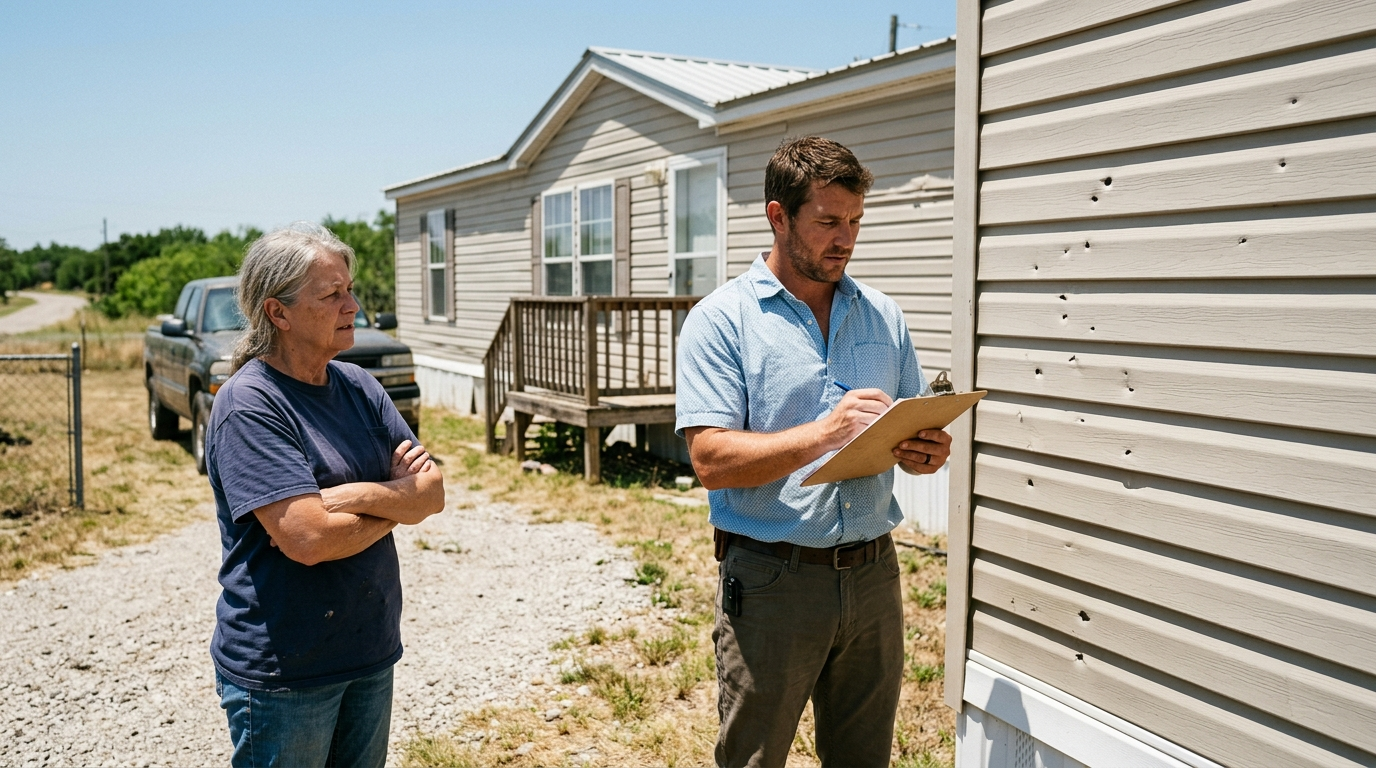
If you own a mobile or manufactured home in Texas, you already know the insurance market for these properties works differently than standard homeowners coverage. Rates vary widely between carriers, coverage terms are not always comparable, and the cheapest quote on the surface does not always deliver the best value when a storm rolls through. Knowing how to compare mobile home insurance quotes the right way can save you hundreds of dollars a year while making sure you are not left short when you need to file a claim.
Why mobile home insurance rates vary so much in Texas
Texas insurers price mobile and manufactured home policies based on a mix of factors specific to this type of dwelling. Understanding what drives your premium makes it easier to spot where you have room to negotiate and where you genuinely need solid coverage.
- Home age and construction standard: Homes built before the HUD Code took effect in June 1976 face sharply higher rates or outright denials from many carriers. Homes built to more recent standards generally qualify for better pricing.
- Location and flood zone: Texas Gulf Coast counties, including Harris County and surrounding areas, sit in high-risk wind and flood zones. A home in a FEMA Special Flood Hazard Area (Zone AE or VE) will carry different base rates than one on higher ground inland.
- Tie-downs and anchoring: Properly anchored homes are less likely to sustain wind damage, and carriers reward that with lower premiums. Some insurers require a tie-down certificate before they will bind coverage at all.
- Coverage type: ACV vs. replacement cost: Actual cash value (ACV) policies pay out depreciated value. Replacement cost policies pay what it takes to rebuild or replace. ACV premiums look cheaper, but a claim payout can leave a significant gap after depreciation is applied to a 20-year-old structure.
- Deductible amount: A higher wind/hail deductible lowers your annual premium but shifts more out-of-pocket cost to you after a storm. In coastal Texas, wind deductibles are often stated as a percentage of insured value (1-5%) rather than a flat dollar amount.
- Credit score and claims history: Texas law permits insurers to use credit-based insurance scores when pricing policies. A clean claims history and solid credit can meaningfully reduce your quoted rate.
What a solid mobile home insurance policy should cover
Before you start collecting quotes, know what you are comparing. A bare-bones policy that skips important coverages is not a deal. It is a liability.
- Dwelling coverage: Pays to repair or rebuild the physical structure of your home after a covered loss such as fire, wind, hail, or vandalism. Make sure the limit is high enough to actually replace the home, not just its depreciated market value.
- Personal property coverage: Covers your furniture, electronics, clothing, and other belongings inside the home. Many mobile home policies cap personal property at 50-70% of the dwelling limit, so check the actual dollar amount.
- Liability coverage: Pays legal costs and damages if someone is injured on your property. Standard limits start at $100,000 , but $300,000 is a smarter floor for most homeowners.
- Additional living expenses (ALE): Covers hotel stays and meals if your home becomes uninhabitable after a covered loss. This coverage is easy to overlook when comparing quotes and can be the difference between a manageable situation and a financial crisis.
- Flood coverage: Flood damage is excluded from virtually every standard mobile home policy. In Texas, you need a separate flood policy, either through the National Flood Insurance Program (NFIP) or the private market. If you live in a low-lying area near Clear Creek, Brays Bayou, or any coastal community, this is not optional coverage.
- Wind and hail endorsements: Some Texas counties, particularly along the coast, require separate windstorm coverage through the Texas FAIR Plan or a surplus lines carrier. Confirm whether wind is included or excluded from any quote you receive.
For a deeper look at flood coverage options, the flood insurance page covers NFIP versus private market choices in plain terms.
A step-by-step process for comparing mobile home insurance quotes
Shopping for the cheapest mobile home insurance near you takes about an hour done properly, but that hour can save you real money and real headaches.
Step 1: Gather your home's specs before you call anyone
Insurers will ask for the year, make, model, size (in square feet), HUD certification number if available, and whether the home is on a permanent foundation or on wheels. Having this information ready speeds up every quote conversation and ensures the figures you receive are accurate rather than ballpark estimates that change at binding.
Step 2: Decide on your coverage limits and deductibles before you shop
Pick your dwelling limit first. If your home would cost $80,000 to replace, do not accept a policy with a $50,000 dwelling limit just because the premium looks attractive. Then set a wind deductible you could genuinely pay out of pocket after a storm. Only then does comparing premiums across carriers make sense, because you are comparing the same coverage, not different products at different price points.
Step 3: Get at least three quotes from different carriers
The mobile home insurance market in Texas includes a handful of specialty carriers alongside standard homeowners companies. Rates between carriers for the exact same home and the exact same coverage can differ by $300 to $600 per year . Getting quotes from at least three companies is the only reliable way to find where the market actually prices your risk.
Step 4: Read the exclusions, not just the premium
Once you have quotes in hand, look at what each policy excludes. Common exclusions in mobile home policies include mold damage, certain foundation issues, trip coverage (coverage while the home is being moved), and older roofs. A policy that excludes wind in a Gulf Coast county or excludes replacement cost settlement is not equivalent to one that includes those features, even if the premium is lower.
Step 5: Ask about discounts before you finalize
Most carriers offer discounts that are not automatically applied. Common ones include:
- Multi-policy discount: Bundling your mobile home policy with an auto policy can cut 5-15% off one or both premiums.
- New home discount: Homes manufactured within the last few years often qualify for lower base rates.
- Protective device discount: Smoke detectors, deadbolt locks, and security systems reduce the likelihood of certain losses, and carriers price that in.
- Senior discount: Several specialty carriers offer preferred rates for homeowners 55 and older who are retired and home more often.
- Claims-free discount: A five-year or longer claims-free record can earn meaningful reductions at renewal.
For more detail on strategies to reduce what you pay, the post on how to lower mobile home insurance costs in Texas walks through each lever you can pull.
Mistakes that cost Texas mobile home owners money
Most coverage gaps that hurt people after a loss trace back to decisions made at quote time. Here are the common ones worth avoiding.
- Choosing ACV over replacement cost without doing the math: A 15-year-old single-wide with a depreciated value of $20,000 that costs $65,000 to replace leaves a $45,000 gap after a total loss if you only carry ACV coverage. Run that math against the premium difference before deciding.
- Skipping flood insurance because you have never flooded: Harris County residents heard this reasoning before Hurricane Harvey in 2017, when homes that had never flooded in decades went underwater. FEMA flood maps are updated regularly and do not capture every risk. Even a low-to-moderate risk flood zone policy through NFIP costs far less than a claim paid entirely out of pocket.
- Not confirming whether wind is included: In the 14 Texas coastal counties served by the Texas Windstorm Insurance Association (TWIA), wind and hail coverage must be purchased separately from your standard mobile home policy. Buying a policy without asking this question directly leaves a significant coverage gap.
- Letting the policy renew without a review: Insurance rates change every year. A carrier that was competitive two years ago may not be today, and your home's replacement cost may have risen with inflation. Reviewing your coverage at each renewal takes 20 minutes and keeps you from overpaying.
- Buying through a single-carrier website: Carrier websites only show you their own rates. An independent agent can request quotes from multiple carriers at once and identify coverage differences you would not catch comparing policies on your own.
What mobile home insurance typically costs in Texas
Statewide averages are a rough guide, but local rates tell the real story. In the greater Houston area and surrounding Gulf Coast counties, annual premiums for a manufactured home with standard coverage run roughly $800 to $1,800 per year depending on home age, location, coverage selections, and carrier. Homes in wind-pool counties or high flood-risk zones sit toward the top of that range. Newer homes on permanent foundations in lower-risk areas can land well below it.
That wide range is exactly why comparing quotes matters. A $600 annual difference on the same coverage, compounded over ten years, is $6,000 . That is real money, and it is available to any homeowner willing to take an hour to shop properly.
If you want context on which carriers are currently writing mobile home policies in Texas and how their coverage terms compare, the post on the best mobile home insurance companies in Texas covers that in detail.
Work with an independent agent to compare your options
JAMCO Insurance is an independent agency, which means we represent multiple carriers rather than a single company. When you ask us to quote your mobile or manufactured home, we pull rates from the carriers actively writing this coverage in Texas and present you the options side by side. You see which carrier offers the best price for the coverage you actually need, not just the coverage they want to sell you.
Our team works with homeowners across the Houston area and the surrounding Gulf Coast region. We know which carriers handle wind in coastal counties, which ones are flexible on older homes, and which ones have a track record of paying claims without a fight. That local knowledge matters when you are comparing quotes, and it matters even more when you need to file one.
If you are ready to compare mobile home insurance quotes and find out what the right coverage actually costs for your home, reach out to JAMCO Insurance at (832) 777-5260 or visit our contact page to get started. You can also learn more about the full range of personal coverage options on our mobile home insurance page. There is no pressure and no obligation. Just a straight comparison so you can make an informed decision.
Get A Quote
At JAMCO, securing your future is easy. Ready to protect what matters? Contact us for a quick quote and personalized insurance options!
Kelly
Speak to Kelly 24/7
Microphone ready
Start your custom insurance quote
Instant answers to your insurance questions
Schedule appointments or follow-ups
Personal Insurance
From auto and homeowners to renters and umbrella policies, we help protect your family and property. Let’s find coverage that fits your life.
Commercial Insurance
We customize policies for your industry's risks, like general liability and workers' comp, ensuring you can run your business worry-free.
Contact JAMCO Insurance
Recent Posts